For twenty years, American policy treated coal as a moral problem to be retired. The atmosphere did not get the memo. Global coal use set records while the United States fatuously dismantled the fuel that had carried its industrial base, and the countries that kept burning it used the advantage to build steel, chemicals, and manufacturing capacity. That is not an environmental success. It is a transfer of industrial power harming Americans.
The numbers are not close. The International Energy Agency estimates global coal demand at about 8.8 billion tonnes in 2024, with another record in 2025. China alone consumes more coal than the rest of the world combined, on the order of 56 percent of global use, nearly 5 billion tonnes. India is second. Together they account for roughly 70 percent of world consumption. Asia-Pacific as a whole is above 80 percent. The United States, after a generation of retirements, is around 5 percent.
China did not phase coal out while America did. In 2025 it commissioned about 78 gigawatts of new coal capacity, the most in a decade, and proposed or reactivated a record volume of additional plants. India added capacity as well. Outside those two countries, new coal construction is now a rounding error. The same year, U.S. coal-plant retirements fell to 2.6 gigawatts, the lowest since 2010, only because federal reliability orders and rising power demand finally interrupted a closure wave. That interruption is a correction, not a reversal of the lost decade.
None of this requires a conspiracy theory about smokestacks. Sulfur dioxide, nitrogen oxides, particulates, and mercury that are real pollutants, and how American plants spent billions controlling them. The falsity is the claim that retiring American coal is a global environmental policy. A tonne of coal burned in Shanxi or Odisha has the same chemistry as a tonne burned in West Virginia or the Powder River Basin. The difference is who captures the steel, the payroll, and the export earnings.
The strategic half of the ledger is metallurgical coal, which is not a power-plant fuel and cannot be swapped for a wind turbine. Blast-furnace steel still depends on coking coal. China is the world’s largest steel producer and, in recent years, the largest importer of metallurgical coal. India produces on the order of 150 million tonnes of crude steel, is targeting 300 million by 2030, and imports roughly 90 percent of the coking coal its furnaces require, because its domestic reserves are too high in ash for steelmaking at scale. Those furnaces are being built to run for decades, overwhelmingly as basic oxygen furnaces, not as electric-arc plants. In 2024 India became the largest destination for U.S. metallurgical coal. The United States is the second-largest exporter, and met coal is now more than half of U.S. coal exports. The resource our domestic policy spent years treating as a relic is the feedstock for the steel expansion of the world’s fastest-growing industrial economies.
That is the asymmetry. American thermal-coal plants were regulated out of existence, and in many states mandated off the grid, while America’s competitors used coal domestic and imported, to hold down industrial power costs and to make the steel, cement, and chemicals that manufacturing requires. U.S. coal’s share of electricity fell from about half at the start of the century to the mid-teens. Cheap shale gas did much of that work, and it should be said plainly: the market moved. But regulation, utility mandates, and capital restrictions accelerated closures past what reliability and price alone required, including plants that still had useful life and interconnection. Europe ran the same experiment and then scrambled for coal and gas when the experiment met a real shortage. Those actions needlessly drove up American and European power prices.
The beneficiaries did not need to draft the statutes. They needed only to decline the same restraint. A country that builds coal plants for system reliability while its rival retires them in the name of climate policy is not confused about national interest. It is practicing it. The slogan that coal is obsolete was never tested against Chinese steel output, Indian blast-furnace construction, or the fact that global coal demand rose as American demand fell. If the objective had been emissions, the negotiation would have been about Chinese and Indian consumption, which dominate the total. If the objective is American economic dominance, voluntarily shrinking a domestic energy resource while rivals expand the same resource is the opposite of strategy.
The correction is already visible, and it should be made permanent. In 2025 U.S. coal consumption rose, IEA puts the increase near 8 percent, other tallies higher, because gas prices moved and because policy stopped treating every retirement as a virtue. Data-center and manufacturing load growth has done what speeches did not: it exposed that a grid cannot retire firm capacity faster than it replaces it. Metallurgical coal should be treated as what it is, a strategic export and an industrial input, not as a synonym for a power-plant debate. Thermal coal that clears modern controls and clears on price belongs in the dispatch stack for as long as reliability requires it. New coal capacity abroad is an argument for American production and American exports, not for another round of domestic closure.
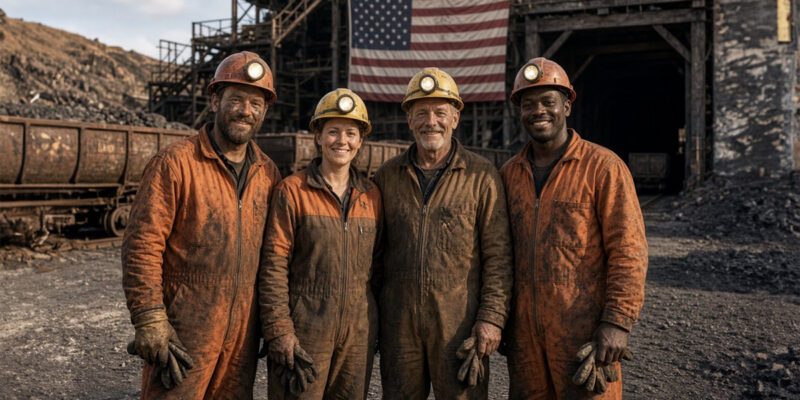
The big hoax is the idea that America serves the climate, or its own workers, by exiting a fuel the rest of the industrial world still uses to build the economy we say we want back. Coal is not a relic. In the hands of our competitors it is a strategic industrial policy. It should be the same in ours as well.
Advertisement
Advertisement
